

Rocco - Fast Cash Advance
Rocco Finance, Inc.
- 4.2
- 1.38K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
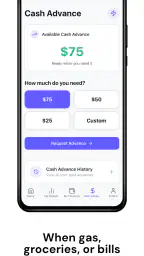
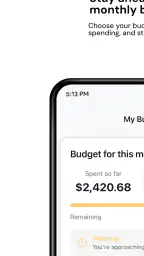
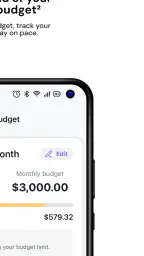
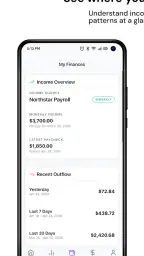
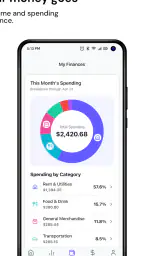
Rocco - Fast Cash Advance Pros and Cons
Pros
- Simple application process with minimal paperwork
- Quick eligibility checks can save time in urgent situations
- Clear repayment schedule helps with budgeting
- Funds may be useful for unexpected short-term expenses
- Mobile access lets users manage requests from their phone
Cons
- APR and fees may be high compared with traditional loans
- Short repayment periods can make installments difficult
- Approval and loan terms vary by applicant and location
- Late payments may lead to additional charges or credit impact
- Availability may be limited depending on state or country
 Analysis by All-app
When an unexpected bill lands between paydays, the hardest part is often not finding a financial app but understanding what it can realistically do for you. I spent time with Rocco - Fast Cash Advance as a finance app from Rocco Finance, Inc., paying particular attention to how clearly it presents its cash-advance and personal-finance purpose, how easy it feels to move around, and where the experience may become difficult for people using it in different situations.
My overall impression is that Rocco is aimed at people who want a direct way to explore short-term financial help rather than a full banking replacement. It is free to download, rated for Everyone, and has built a noticeable audience with over one hundred thousand installs. That reach matters, but it should not be confused with a promise that every applicant will receive an advance or that an advance is automatically a good financial decision.
I also found that the most important part of using an app like this is not speed alone. A cash advance can solve a timing problem while creating another repayment obligation. Rocco is therefore most useful when I treat it as a tool for reviewing an immediate option carefully, not as extra income.
How the app presents money information
I focus on how the app frames a possible cash advance, because that is the decision with the greatest practical impact. I look beyond the amount that might solve an immediate shortfall and consider what information a person needs to judge whether the commitment fits their next pay cycle. That framing leads into the more hands-on question of using Rocco when money is tight.
Readability and navigation come first
Financial apps need to explain money in plain language because a confusing screen can lead to a costly misunderstanding. Rocco’s identity is easy to grasp: it focuses on cash advances and personal-finance services rather than trying to look like a complete investment platform, credit-card manager, or traditional checking account. That narrow purpose gives a new user a reasonable starting point.
In my experience, the best way to approach the app is slowly. I would read each screen from top to bottom, check every amount and date presented, and avoid treating a prominent action button as an instruction to continue automatically. This is especially important when the user is tired, anxious, or trying to solve a problem during a short break at work.
The app’s current version is 3.0.0, and it runs on devices using Android 8.0 or later. That makes compatibility an early practical question. Someone using an older phone should check the operating-system requirement before planning around Rocco, while a person with a supported device can at least know whether the app is technically available before spending time on an application flow.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Text-heavy finance screens can be difficult for people with low vision, reading difficulties, or limited financial vocabulary. I recommend increasing the phone’s system text size before starting, then checking whether important labels remain visible rather than being cut off or pushed out of view. If a screen becomes crowded after enlargement, that is a sign to slow down and review the information in another setting instead of rushing through it.
One useful habit is to separate “what Rocco is asking me to provide” from “what Rocco is offering me.” I would make a quick note of the requested information, the amount under consideration, and any repayment details shown during the process. That small pause makes it easier to spot a mismatch between the amount I need and the amount I might actually have to manage later.
Navigation for different abilities and attention levels
Someone with cognitive fatigue may not struggle with tapping buttons but may struggle with keeping several financial details in mind. For that user, Rocco is easier to approach in short sessions: first understand the purpose, then review eligibility-related questions, and only afterward decide whether continuing makes sense. There is no benefit in completing a financial form while distracted and then trying to remember what was accepted.
Users who rely on screen readers, magnification, voice control, or other phone-level tools should test the key screens before entering sensitive information. I would pay attention to whether controls are announced in a meaningful order, whether labels describe their purpose, and whether focus moves predictably. These checks are more valuable than assuming that a modern finance app will work equally well with every assistive setup.
For people who prefer visual simplicity, the app’s focused purpose is a strength. It is not presenting itself as a giant collection of unrelated financial products. However, a focused purpose does not remove the need to inspect every condition shown during use. A simple-looking interface can still contain decisions that deserve careful reading.
Motor and sensory considerations
Cash-advance applications may involve repeated scrolling, typing, selecting options, and reviewing personal details. That can be tiring for users with limited dexterity, tremors, joint pain, or difficulty making precise taps. I would use the app on a stable surface, keep the phone in a comfortable position, and avoid trying to complete the process while walking, commuting, or carrying other items.
Voice input may reduce typing for some people, but it is not automatically suitable for private financial information. Dictating personal details in a public place can expose information to nearby listeners, and speech recognition may mishear names, addresses, or numbers. A quieter environment and a final visual check are sensible safeguards, especially when a single character can affect an application.
Bright screens, small text, motion, or dense layouts can also create sensory friction. I would use the phone’s display settings, a quieter environment, and a short break if the review process becomes visually tiring. The important point is that accessibility is partly about the app and partly about the conditions in which it is used. Rocco may be manageable at a desk but much harder to use on a noisy bus with glare on the screen.
Motor access also affects the decision itself. If a user has difficulty scrolling back to review an earlier section, they may accept something without seeing the full context again. I suggest taking screenshots only when doing so is safe and appropriate, or writing down the key figures and obligations in a separate note. The goal is to create a record that can be checked without repeatedly navigating a demanding screen.
Using Rocco in real financial situations
I approach a cash advance as a response to a specific timing problem, not as spare income. In the situations I consider next, I weigh the immediate need against the repayment and the user’s ability to review details without rushing. The same option can be useful in one carefully planned moment and a poor fit when it becomes a recurring way to cover essentials.
Situational access matters more than convenience
Imagine that a utility payment is due before payday and the user has already checked their budget. They open Rocco at home, where the screen is easier to read, compare the amount they need with the repayment obligation shown, and decide whether the short-term option fits their next pay cycle. That is a sensible use case because the person is treating the app as one possible bridge after reviewing the underlying problem.
Now change the situation: the same person is in a crowded workplace, worried about a late payment, using an older phone, and trying to finish quickly. The same app may become much harder to use. Glare, noise, limited privacy, and stress can all reduce the quality of the decision. In that context, I would wait until the user can review the terms calmly, even if the financial problem feels urgent.
Rocco can also be relevant to users who do not want to visit a branch or make a phone call. That digital route may be more comfortable for someone with social anxiety, hearing-related communication barriers, limited transport, or a schedule that makes traditional office hours inconvenient. At the same time, a digital process can be less helpful for someone who needs a person to explain unfamiliar financial language in real time.
People with limited data access should consider the practical setting before starting. A broken connection or interrupted session can be frustrating when the user has already entered information. I would use a reliable connection and avoid switching repeatedly between applications. This is not a claim about a particular network requirement; it is simply a sensible way to reduce interruptions during any sensitive financial task.
What I would check before continuing
The first question is not “Can I get money quickly?” but “What exactly will this decision require from me afterward?” I would look for the amount received, the amount to be repaid, the timing, and any other clearly presented conditions. If I could not understand those points, I would stop and seek clarification rather than relying on a guess.
The second question is whether the need is genuinely temporary. A cash advance may be reasonable for a one-off timing gap when the next income is already expected and the repayment will not interfere with essentials. It is a poor fit when the user is borrowing repeatedly for groceries, rent, utilities, or existing debt. In that pattern, a budget review, creditor arrangement, community support service, or qualified financial counselor may be more useful than another advance.
The third question is whether the user has a backup way to track the obligation. I would put the repayment date and amount into a calendar or budgeting tool immediately, without assuming the app will be my only reminder. This is one of the most practical workflows I can recommend: separate the decision from memory, because financial stress makes it easy to forget a commitment once the immediate crisis has passed.
Finally, I would protect privacy during the process. I would not complete an application while someone else can see the screen, and I would avoid sharing login or financial details with friends who offer to “help” by taking over the phone. A trusted person can assist with reading or navigation while the account holder keeps control of sensitive actions.
Where it differs from usual alternatives
Compared with asking a bank for an overdraft or personal loan, Rocco is positioned around a faster, more focused cash-advance experience. That can be appealing when the problem is timing rather than a long-term borrowing plan. A bank or credit union may be a better place to compare broader borrowing options, discuss repayment in detail, or build an ongoing relationship.
Compared with a budgeting app, Rocco addresses access to a possible advance rather than simply showing spending patterns. A budgeting tool may be the better first step when the user does not know where their money is going or wants to prevent the same shortfall next month. Using a cash-advance app without understanding the budget can treat the symptom while leaving the cause untouched.
Compared with borrowing from a friend or family member, an app may feel more private and less socially uncomfortable. The trade-off is that a personal arrangement may allow more flexible conversation if repayment becomes difficult, whereas a formal financial obligation should be treated with the seriousness of any other scheduled payment. I would not choose one automatically; I would compare privacy, clarity, consequences, and the effect on the relationship.
The app’s average rating is 4.2 from around four thousand ratings, with roughly one thousand four hundred written reviews. I see that as evidence that many people have engaged with it, not as proof that it will suit every financial situation. Reviews can help identify recurring usability patterns, but they cannot replace reading the terms shown for an individual application.
Remaining barriers and who should skip it
The biggest barrier is financial rather than technical: an advance still has to be repaid. A clean interface cannot make an unaffordable obligation safe. Anyone already relying on several short-term borrowing services should be particularly cautious, because adding another payment may make the next pay period tighter.
Rocco may also be the wrong choice for a user who needs a large, planned loan, detailed debt counseling, cash-management tools, or a traditional bank account. Its cash-advance focus does not make it a substitute for those services. Someone comparing long-term borrowing costs should look at established lending institutions or speak with a qualified adviser instead of choosing based only on speed.
Accessibility needs can create another barrier. Users who require guaranteed compatibility with a particular assistive technology should test the app directly on their own device and stop if essential controls are not usable. The Everyone age rating describes the intended content audience, but it does not guarantee that every visual, motor, hearing, or cognitive need will be met.
There is also a language and comprehension barrier for anyone unfamiliar with financial terms. I would not ask a child to manage the process simply because the content rating is Everyone, and I would not encourage an adult to accept an offer they cannot explain in their own words. If the amount, timing, or repayment obligation is unclear, that lack of understanding is itself a reason to pause.
My inclusive verdict
After using Rocco as a finance app, I see its strongest role as a focused digital option for someone facing a short-lived cash gap who can read the details, protect their privacy, and repay without sacrificing essentials. Its free availability and clear cash-advance identity make it approachable, while its current Android compatibility gives many users a straightforward way to try the experience.
For inclusive use, I would choose a calm environment, enlarge text if needed, keep the phone stable, use assistive tools cautiously, and record the repayment obligation outside the app. Those steps do not replace proper accessibility testing, but they can make the decision process more deliberate for users with different abilities or temporary limitations.
My recommendation is conditional: use Rocco as a carefully reviewed short-term option, never as a routine income replacement. I would recommend it to a friend only after asking whether the need is temporary and whether the next repayment is genuinely affordable. If the answer is uncertain, a budgeting review, a bank or credit-union conversation, creditor assistance, or independent financial guidance is likely to be the more inclusive and sustainable next step.
Rocco Finance, Inc. has created an app with a clear purpose and a meaningful user base, but the responsibility remains with the user to understand the commitment. That balance is the key to judging Rocco - Fast Cash Advance: convenient access can be helpful, yet careful reading, privacy awareness, and an honest look at the next pay cycle matter more than completing the process quickly.
Frequently Asked Questions
What is Rocco - Fast Cash Advance?
Rocco - Fast Cash Advance is a financial app designed to help eligible users request short-term cash advances through a mobile device. After creating an account and providing the requested personal and financial information, users may receive an offer based on the app’s assessment. It is important to understand that approval, advance amounts, fees, and repayment terms can vary by applicant and location.
How do I apply for a cash advance with Rocco?
To apply, you generally need to download the app, register an account, verify your identity, and connect or provide information about your income and bank account. Rocco then reviews the submitted details to determine whether an offer is available. Before accepting anything, carefully check the total repayment amount, any membership or transaction fees, the due date, and the cancellation conditions.
How much money can I borrow, and how quickly will I receive it?
The amount available through Rocco depends on factors such as your income, banking history, eligibility, and the information supplied during registration. A cash advance is not guaranteed, and the maximum amount may differ between users. If approved, delivery speed can also depend on your bank, processing times, weekends, and whether an optional expedited transfer fee applies.
What fees and repayment terms should I expect?
Before using Rocco, review all costs shown in the app, including possible subscription charges, service fees, expedited-transfer fees, late fees, or other applicable expenses. The repayment date and method should be clearly displayed before you accept an advance. Since terms may change according to your offer and state or country, never rely only on promotional wording; read the final agreement carefully.
Is Rocco - Fast Cash Advance safe to use?
Rocco may use security measures to protect account and financial information, but no online service can eliminate every privacy or security risk. Only download the app from an official store, verify the developer, and review its privacy policy and requested permissions. Avoid sharing login codes, monitor your bank account for unexpected withdrawals, and contact official support if you notice suspicious activity.


